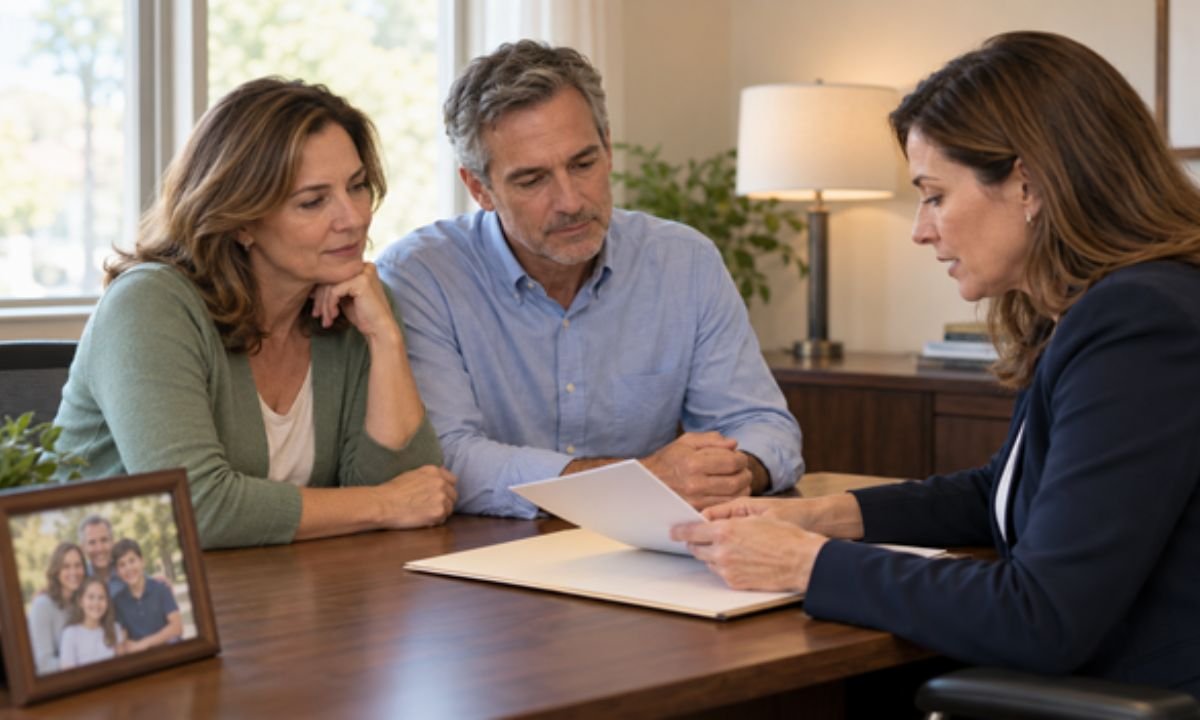
In a blended family, estate planning involves providing for your spouse while protecting the assets you want your children to inherit. If either of you has children from an earlier relationship, clear arrangements can help ensure both priorities are addressed.
For example, you might want your spouse to continue living in your home while ensuring your children inherit it later. Carefully drafted documents can explain those wishes and reduce uncertainty before a loss leaves family members facing difficult financial decisions.
Start With Specific Family Goals
List everyone you want to provide for, including biological children, adopted children, and stepchildren. Then discuss what support should look like immediately after your death and years later.
Useful questions include:
- Should your spouse receive assets outright, ongoing income, or both?
- Should children inherit immediately or after your spouse dies?
- Who should receive family heirlooms?
- How should unequal financial needs affect distributions?
Equal shares are not the only reasonable approach. The key is to make your choices clear rather than expecting relatives to interpret informal promises.
Understand New York’s Default Rules
Without a valid will, New York law determines who inherits assets passing through your estate. When a spouse and children survive you, the spouse generally receives $50,000 plus half the balance, and the children share the remainder.
Stepchildren generally do not inherit under those rules unless legally adopted. A surviving spouse may also have an elective share right that affects a plan, so leaving everything to children requires careful legal review.
If you search for an “estate planning attorney Long Island,” ask how those rules apply to your family and property. Bring any existing wills, trusts, and marital agreements.
Consider a Trust for Shared Priorities
Leaving assets outright to your spouse usually gives that spouse control over their later use and distribution. A promise to leave remaining property to your children may not provide the protection you expect.
A properly structured trust can provide support for a spouse while directing remaining assets to children later. Its terms should explain permitted distributions, housing arrangements, and who manages the property.
A living trust attorney can discuss whether a trust fits your goals and how it must be funded. A revocable trust alone does not automatically prevent changes or guarantee that children will inherit.
Coordinate Accounts and Beneficiaries
Review life insurance, retirement accounts, and jointly owned property alongside your will. These assets may transfer through beneficiary designations or ownership arrangements instead of the will.
Ask whether existing designations match your intended plan and whether spousal consent requirements apply. Don’t assume updating one document changes every account.
Keep copies of beneficiary confirmations with your estate records. Review them after remarriage, a birth, a death, or other significant family changes.
Choose Decision Makers Carefully
Select an executor and, if needed, a trustee who can manage records, follow instructions, and communicate fairly. A neutral trustee may help when a surviving spouse and children have competing financial interests.
For minor children, discuss guardian nominations and inheritance management separately. Also update powers of attorney and healthcare documents to identify your chosen agents.